Klarna vs Affirm: Which BNPL Service Is Better?

Last reviewed: September 29, 2026

Quick answer: Klarna is better for everyday shopping flexibility with its browser extension and pay-in-four option at virtually any store. Affirm is better for large planned purchases where you need fixed monthly payments over 3 to 60 months. Both report to credit bureaus, but Affirm reports more aggressively to Experian and TransUnion. Klarna charges late fees up to $7; Affirm charges none. Choose based on what you buy and how long you need to pay.

What Is the Core Difference Between Klarna and Affirm?

Klarna is a flexible shopping tool. Affirm is a financing tool. Klarna’s strength is its pay-in-four option and browser extension that works at almost any online retailer. Affirm’s strength is structured installment loans with fixed APRs for larger purchases at partner merchants like Amazon, Walmart, and Peloton.

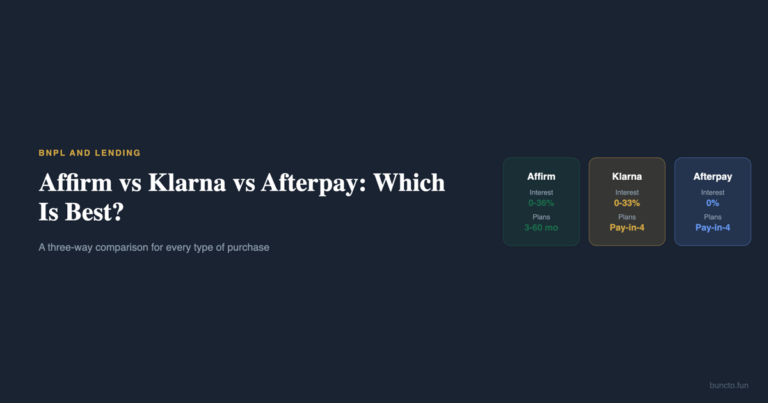
Klarna lets you split any purchase into four interest-free payments over six weeks, or choose monthly financing at 0% to 29.99% APR for longer terms. Its browser extension creates a one-time virtual card at checkout, which means you are not limited to Klarna’s merchant network. Affirm offers pay-in-four at select merchants, but its primary product is installment loans from 3 to 60 months at 0% to 36% APR.

The practical result: Klarna suits frequent online shoppers who want a single tool across many stores. Affirm suits people financing a specific large purchase with predictable monthly payments. For a broader three-way comparison including Afterpay, see our full BNPL comparison. Our research methodology explains how we evaluate these products.

Which Charges Less in Fees and Interest?

Affirm charges zero late fees on all plans. Klarna charges up to $7 per missed payment. On interest, both can be free or expensive depending on the plan. The fee and interest structure is the biggest practical difference between the two providers.

Feature Klarna Affirm
Pay-in-4 interest 0% always 0% at select merchants
Monthly financing APR 0%-29.99% 0%-36%
Late fees Up to $7 $0
Late fee grace period ~10 days N/A (no fees)
Minimum purchase No minimum for pay-in-4 Varies by merchant
Maximum loan amount Varies by approval Up to $17,500
Early payoff penalty None None

For short-term purchases paid in four installments, both are free. The difference emerges when something goes wrong. Miss a Klarna payment and you pay up to $7 per installment plus a frozen account. Miss an Affirm payment and you pay nothing in fees, but the delinquency hits your credit report. Affirm’s approach is arguably more consequential despite costing less upfront — credit damage outlasts a $7 fee. For more on what happens when payments slip, read our guide on missed BNPL payments.

How Does Credit Reporting Differ Between Klarna and Affirm?

Affirm reports to both Experian and TransUnion. Klarna reports to TransUnion only. Affirm, Klarna, and Afterpay all report to at least one credit bureau as of 2025, according to provider announcements. BNPL late payments began affecting credit reports more broadly that year, changing the calculus for every user.

Affirm’s dual-bureau reporting means both on-time and late payments appear on two of your three credit files. Longer-term Affirm loans of 6 to 60 months function as installment tradelines, adding payment history depth similar to an auto loan or personal loan. This helps people with thin credit files build history but also means delinquency appears in two places.

Klarna’s single-bureau reporting to TransUnion means the impact is narrower. A missed Klarna payment affects your TransUnion file but not Experian or Equifax. On-time Klarna payments similarly only build history at TransUnion. If you are actively building credit, Affirm’s broader reporting is more valuable. If you want minimal credit footprint, Klarna’s narrower scope is less risky.

Which Works at More Stores?

Klarna works at virtually any online store through its browser extension and one-time virtual card. Affirm is limited to its merchant partner network unless you use its virtual card feature. This is Klarna’s strongest competitive advantage.

Klarna’s browser extension detects online checkouts and offers to create a one-time Visa card number funded by your Klarna plan. The merchant never knows you used Klarna — they see a normal card payment. This works at any store that accepts Visa online, regardless of whether the store has a Klarna partnership.

Affirm integrates directly at checkout with hundreds of major retailers: Amazon, Walmart, Target, Peloton, Expedia, and others. The Affirm app also offers a virtual card for use at non-partner merchants, but availability and terms vary by user. The experience is smoother at partner merchants where Affirm is built into the checkout flow with transparent APR disclosure.

My view: if you shop across many different stores, Klarna’s universal coverage makes it the more practical daily tool. If you primarily shop at major retailers that already offer Affirm at checkout, the integrated experience is cleaner. Read our complete BNPL guide for more on how merchant integration works.

Which Is Better for Large Purchases Over $500?

Affirm is the clear winner for large purchases because it offers structured installment loans up to $17,500 with fixed monthly payments over 3 to 60 months. Klarna’s monthly financing exists but caps out earlier and has less transparent pre-approval.

Affirm shows your exact APR, monthly payment, and total cost before you commit. A $1,000 purchase at 0% APR over 12 months costs exactly $83.33 per month with no surprises. At 15% APR over 12 months, the total cost is roughly $1,083. The terms are fixed at checkout and do not change.

Klarna’s monthly financing works similarly in theory but is less widely available for larger amounts. Klarna’s pay-in-four option splits any purchase into four payments over six weeks — fine for a $200 jacket, but paying $250 every two weeks on a $1,000 purchase strains most budgets. For purchases that need months to pay off, Affirm’s longer terms and fixed-rate structure are better designed.

Which Should You Actually Choose?

Choose Klarna if you want one BNPL tool that works everywhere for everyday purchases. Choose Affirm if you are financing a specific large purchase and want fixed monthly payments with no late fees. Most people benefit from picking one and sticking with it rather than juggling both.

Klarna fits the casual shopper who splits $50 to $300 purchases across many different stores. Its browser extension removes the merchant limitation. Its pay-in-four is simple and interest-free. The downside is late fees and single-bureau reporting.

Affirm fits the planned buyer who is financing furniture, electronics, travel, or fitness equipment at a specific retailer. Its longer terms, no late fees, and dual-bureau reporting treat BNPL more like a real financial product. The downside is limited merchant coverage without the virtual card and potentially higher APRs on longer loans.

I think Affirm is the better product overall because its no-fee policy and transparent terms treat users more fairly. Klarna’s convenience edge is real, but paying $7 in late fees on a $30 purchase is a worse deal than Affirm’s fee-free approach. Both providers are legitimate tools when used for planned purchases you can afford. Our research methodology covers how we compare these products head to head.

Sources

  • Affirm — product terms, APR disclosure, credit reporting policy (affirm.com)
  • Klarna — payment options, fee schedule, TransUnion reporting (klarna.com)
  • Experian — BNPL reporting integration (experian.com)
  • TransUnion — BNPL data inclusion
  • Consumer Financial Protection Bureau — BNPL market report (consumerfinance.gov)
James Whitfield

James Whitfield

Fintech Analyst

James Whitfield covers digital banking, credit products, and financial technology for Buncto. A former banking operations analyst, he pivoted to consumer fintech journalism after watching neobanks reshape how everyday Americans manage money. James researches by reading regulatory filings, testing financial products firsthand, and tracking how fintech apps handle deposits, credit reporting, and dispute resolution. His work focuses on explaining the mechanics that marketing pages leave out.

People who track every purchase in a budgeting app often set aside a small fun money line for entertainment, and a few minutes spinning reels at LuckyLand Slots can sit inside that line without touching any savings goal.

Reading the fee schedule before opening a new checking account is a smart habit, and the same careful reading helps when comparing coin packages and daily rewards at Crown Coins Casino before spending anything at all.

Payment apps made splitting a dinner bill with friends feel effortless, and social casinos borrow that group spirit with shared tournaments and coin drops that many players compare at Crown Coins.

App-first users who already move money between a neobank and a card account like to understand deposit and withdrawal methods upfront, which is why they review the banking page at Ignition Casino before joining.

Building credit rewards patience and steady habits over quick wins, and players who carry that mindset to the tables tend to set a firm session budget before they log in at Ignition.

Many readers who follow mobile banking news also follow game-day lines on their phones, and DraftKings is a familiar app for those who like to compare odds with the same care they give to comparing savings rates.

Entertainment does not always need to come out of a checking balance, and plenty of budget-minded readers enjoy free Gold Coins and casual slots at Chumba Casino on a slow evening.

Digital wallets turned everyday payments into something closer to a social feed for many people, and Vegas World brings a similar social layer to casino-style games with gifts, chat and friends lists that feel familiar.

Trying a budgeting app on a free plan before upgrading is sensible, and in the same way Vegas World free slots lets players learn how reels and bonus rounds work with no deposit required.

After an hour of reconciling transactions and reviewing autopay settings, some readers want a low-stakes way to switch off, and Casino World free slots offers a simple library of free reels for exactly that.

Savers who compare banks on transfer speed, app quality and customer support usually compare casinos on payout speed and game range as well, and NeoSpin Casino often appears in those side-by-side reviews.

Flexible deposit options are the first thing many app-first spenders check on any gaming site, and Yabby Casino is one of the names they look at when they want card and digital payment choices.

Quick sign-ups and a clean mobile layout are what people expect from a modern finance app, and sweepstakes sites like Yay Casino have drawn a following by offering that same easy feel.

Sports fans who manage their money from one dashboard often want one account for both game lines and casino play, and BetUS is a long-running option they compare on banking methods.

Just as a careful borrower checks that a lender is properly licensed, careful bettors check licensing before anything else, and Betway is a recognized name many of them start with.

Readers who prefer an established bank over an untested startup often bring that same preference to gaming too, choosing well-known regulated brands like BetMGM in the states where it legally operates.

Every savings app explains risk levels before you invest, and slot games have their own version called volatility; players curious about how different games feel can try them at Casino World.

Cashback apps reward people for coming back each day, and social casinos use a similar daily login loop; Lavish Luck Casino is one of the sweepstakes sites built around that kind of routine reward.

Learning to read a credit report properly takes practice, and so does reading a poker table; players who want to sharpen that skill without spending any real money often practise their hands at Replay Poker.

Some of our readers treat a social casino as a light break after a long budgeting session, and Chumba remains one of the most familiar sweepstakes names for that kind of casual play.

Free chips and no cash-out pressure make DoubleDown Casino a comfortable pick for people who want the fun of spinning reels on a quiet night while keeping their checking account completely out of it.

Early adopters try new fintech apps before their friends do, and the same curiosity leads them to newer sweepstakes casinos such as Zula Casino to see how they compare with older names.

People who manage bills and a sportsbook from the same phone often like one brand for betting and casino tables, which is a big part of the appeal of DraftKings Casino in legal states.

Rewards programs that separate points from cash will feel familiar to any credit card holder, and Pulsz Casino uses a similar split with Gold Coins for play and Sweeps Coins for prizes.

Not every app needs a tutorial, and after a day spent comparing loan offers or card terms, readers looking for something simple sometimes unwind with the casual games at Zone Casino.

Bettors who keep part of their balance in digital currency often prefer sportsbooks that accept it directly, and MyBookie is a name they commonly compare for deposits and game-day markets.

Bright themes and quick spins give LuckyLand a playful feel, and casual players can join in without linking a bank account or entering card details just to get started on a few games.

Readers who regularly send money abroad through international payment apps tend to know the major European betting brands, and bwin is one they mention when comparing sportsbooks across different markets.

A sensible budget sets a spending cap before the month begins, and a sensible player sets a session cap before the first spin; that habit applies just as well at Betway Casino.

Daily coin bonuses at LuckyLand Casino work a little like a savings app round-up feature, a small top-up simply for showing up, which keeps casual players returning between their regular money check-ins.

Live odds shift as quickly as a trending stock on a mobile trading app, and fans who enjoy following those moves in real time often keep game lines open on DraftKings Sportsbook.

Fraud alerts taught many app users to double-check every login page before typing a password, and that habit matters just as much in gaming, for example when signing in to Crown Coins.

Card holders who like to know exactly how and when deposits clear tend to compare payment options before anything else, and BetUS Casino is one of the casino sites that often lands on that shortlist.

Fintech brands tend to win users with friendly design and a strong community around the product, and the sweepstakes site McLuck leans into that same approach with colorful games and regular coin promotions.

Anyone who has spotted surprising fine print in a buy now pay later offer tends to apply the same healthy skepticism to gaming promotions, reading the coin package terms closely at WOW Vegas first.

Building core features in house is usually a sign of a serious fintech team, and in gaming a similar idea applies at High 5 Casino, which develops many of its own slot titles rather than licensing them.

Few gaming brands are as linked to digital currency culture as Stake.us, which is why it comes up often among readers who already hold a crypto wallet next to their banking app.

Sweepstakes sports predictions are a fairly new category, and readers who enjoy following match results on the same phone they use for mobile banking sometimes try Sportzino for a free-to-play angle.

The name sounds like it could belong to a savings jar app, but Fortune Coins is actually a sweepstakes casino where players collect coins through daily logins and promotions rather than through deposits.

Savings challenges with friends turn a routine habit into a shared goal worth chasing, and Funrize brings that same competitive spirit to casual play through regular tournaments, leaderboards and community events.

Readers who test a new payment app with a small transfer before trusting it with more often test new gaming platforms the same careful way, starting with free coins at Modo Casino before going further.

A new app and a new casino lobby share something in common: early users want to look around before committing, and Spree Casino is one of the newer sweepstakes lobbies they explore.

Players who prefer one login for sports picks and casino games, much like one app for checking and savings, often compare the options at Legendz Casino against other social gaming sites.

Long before most mainstream payment apps supported any kind of digital currency, Bitcoin users were already funding accounts at Bovada, which keeps it a familiar name among early crypto adopters and fintech fans.

A relaxed lobby and straightforward banking options make Cafe Casino an easy pick for readers who want a short slot session after a long day spent reviewing statements, bills and autopay dates.

Holding more than one kind of digital currency alongside a regular bank account is common among app-first savers, and Wild Casino is one of the casinos they compare for its range of accepted coins.

Slot fans who think in terms of hit rates and variance, much the way careful savers think about yield and risk, often spend time browsing the large and varied reel library at Slots.lv.

Sports, casino and poker under a single account appeals to readers who dislike juggling apps the way they dislike juggling too many bank logins, and BetOnline is often named for that mix.

Readers who value a long history when choosing a bank often value the same thing in gaming, which is why an established brand like Borgata Casino gets attention in regulated states.

A name with real history behind it builds trust in finance and in entertainment alike, and Golden Nugget brings a long-standing casino brand into online play for adult players located in legal states.

Shoppers who already earn rewards through store cards and retail apps may recognize the brand behind Fanatics Casino, which links its casino rewards to a wider fan and merchandise program they might already use.

Clear bonus terms are the gaming version of a plain-language loan disclosure, and players who value that kind of honest transparency in their financial apps often review the offers at BetRivers too.

Loyalty points that keep their value across a wider network of hotels and venues work a bit like a travel rewards card, which is part of why regular players are drawn to Caesars Casino.

Poker rewards patience and careful risk management, two qualities anyone paying down a balance learns over time, and the social poker app WSOP is an easy place to practise them.

Sweepstakes poker lets players sit at real tables without going through the usual deposit route, and budget-conscious readers who are curious about poker strategy often start their learning at Global Poker.

Testing a new investing app with a demo account before adding real funds is standard practice, and practising poker for free at Replay Poker follows the same low-risk approach to learning a new skill.

Private clubs and invite-only tables echo the closed groups that many app communities and money forums run on, which is one reason poker fans who prefer smaller circles choose to use ClubGG.

Privacy settings matter to anyone who manages money online, and anonymous tables that limit tracking by stronger regulars are a common reason why careful, privacy-minded players decide to choose Ignition Poker.

Fast-fold tables move quickly, much like instant payments landing in a mobile wallet within seconds, and players who enjoy that kind of high-tempo session often check out the poker rooms at Bovada Poker.

Big guaranteed tournaments attract players in much the same way a strong signup offer attracts new bank customers, and ACR Poker is well known among online players for its busy tournament schedule.

Flexible deposit methods and a steady flow of cash games make BetOnline Poker a regular pick among poker players who already manage much of their everyday money through banking and payment apps.

Some brands become the default name in their category, the way certain payment apps did for sending money to friends, and for many online players that name in poker is still PokerStars.

Hand histories and stats tools give poker players the same kind of insight that spending dashboards give careful budgeters, and GGPoker is popular with players who prefer a data-driven style of play.