Quick answer: Affirm is best for large purchases with fixed monthly payments at 0% APR. Klarna is best for flexible shopping with pay-in-four and broad merchant availability. Afterpay is best for fashion and retail with its simple four-payment split and no interest charges. All three now report to at least one credit bureau as of 2025, so your choice affects your credit profile regardless of provider.
How Are Affirm, Klarna, and Afterpay Different?
Affirm focuses on longer-term financing with fixed rates. Klarna offers the widest range of payment options. Afterpay sticks to short-term pay-in-four with no interest. Despite surface similarities, these three BNPL providers serve different use cases and charge differently.
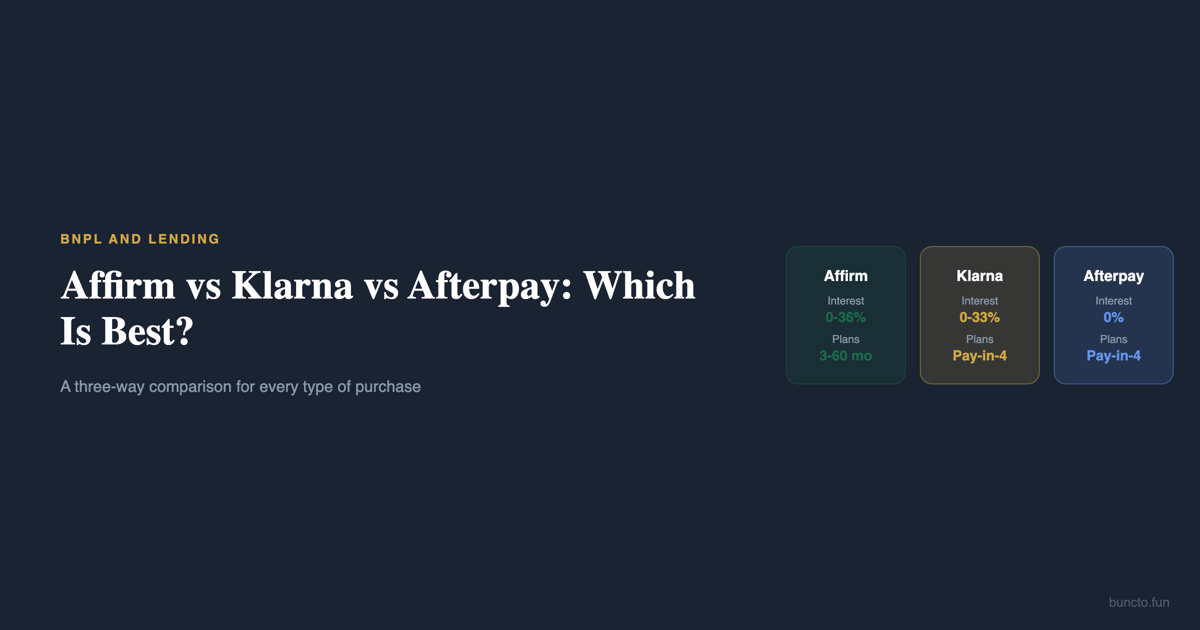
Affirm offers installment loans from 3 to 60 months with APRs ranging from 0% to 36%, depending on the merchant and your creditworthiness. Klarna provides pay-in-four (interest-free), monthly financing (up to 36 months), and a one-time card for any online store. Afterpay only offers pay-in-four — four equal payments every two weeks, always interest-free.
The merchant network differs significantly. Affirm partners with major retailers like Amazon, Walmart, and Peloton for point-of-sale financing. Klarna’s browser extension works at virtually any online store. Afterpay has strong coverage in fashion and beauty retailers. Your shopping habits determine which provider you encounter most. See our complete BNPL guide for how each integrates at checkout.
Which BNPL Provider Has the Lowest Cost?
Afterpay is the cheapest for short-term purchases because it never charges interest. Affirm can be the cheapest or most expensive depending on whether you qualify for 0% APR. The cost comparison depends entirely on the payment timeline and your credit profile.
| Feature | Affirm | Klarna | Afterpay |
|---|---|---|---|
| Pay-in-4 (interest-free) | Yes, at select merchants | Yes | Yes (only option) |
| Monthly financing | 3-60 months | Up to 36 months | No |
| APR range | 0%-36% | 0%-29.99% | 0% (always) |
| Late fees | -bash | Up to | Up to (capped at 25%) |
| Credit check | Soft pull | Soft pull | No credit check |
| Credit reporting | Experian, TransUnion | TransUnion | Equifax |
| Virtual card | Yes | Yes | Limited |
| Browser extension | No | Yes | No |
| Best for | Large planned purchases | Everyday flexible shopping | Fashion and retail |
On a 00 purchase paid over 6 months, Affirm at 15% APR costs roughly 2 in interest. The same 00 on Afterpay’s pay-in-four costs -bash but must be repaid in 6 weeks. Klarna’s monthly financing at a comparable rate falls between the two. For anything you can repay within 6 weeks, Afterpay or Klarna’s pay-in-four are the clear winners.
Which Reports to Credit Bureaus and Does It Matter?
All three report to at least one credit bureau as of 2025. Affirm reports the most aggressively, sending data to both Experian and TransUnion. Klarna reports to TransUnion. Afterpay reports to Equifax. BNPL late payments began affecting credit reports more broadly in 2025, according to credit bureau announcements.
This changes the calculus entirely. Before 2025, BNPL was functionally invisible to your credit score — missed payments had no lasting consequence beyond losing access to the app. Now, a single late payment on any of these three platforms can appear on your credit report and lower your score by 60 to 100 points.
The flip side is that on-time payments now build your credit history. Affirm’s longer-term loans function like traditional installment loans on your report, adding payment history depth. This matters most for people with thin credit files — a 12-month Affirm loan paid on time adds 12 positive payment entries. Our BNPL credit impact guide covers exactly what appears on your report from each provider.
Which BNPL Provider Has the Best Merchant Coverage?
Klarna wins on coverage because its browser extension and one-time card work at virtually any online retailer, not just partner merchants. Affirm and Afterpay are limited to their merchant networks unless you use a virtual card feature.
Affirm’s direct merchant integrations include Amazon, Walmart, Target, Peloton, Expedia, and several hundred other major retailers. The checkout option appears automatically when available. Affirm also offers a virtual card through its app for use at non-partner stores, though approval and terms vary.
Afterpay’s network skews heavily toward fashion, beauty, and lifestyle brands — Sephora, Urban Outfitters, Adidas, and similar retailers. Its coverage outside these categories is thinner. Klarna’s browser extension solves the coverage problem entirely by creating a one-time virtual card at checkout on any site. This flexibility makes Klarna the most versatile option for shoppers who buy across many different stores.
Which Is Safest If You Might Miss a Payment?
Affirm is the safest because it charges zero late fees on any plan. If you are concerned about missing a payment, Affirm’s no-fee policy means the only consequence is credit reporting — which is serious, but at least you are not paying penalty charges on top of it.
Afterpay is the riskiest for missed payments. Its late fee per installment, applied immediately with no grace period, stacks fast on multiple orders. If you have three active Afterpay orders and miss a payment cycle, you could owe 4 in fees within days. Klarna falls in the middle with a roughly 10-day grace period before fees apply and a maximum per missed payment.
All three providers freeze your account after missed payments, preventing new purchases until you catch up. This is actually a useful guardrail — it stops the debt from growing. Affirm’s approach of no fees plus credit reporting treats BNPL like a real financial obligation. Afterpay’s fee-heavy model penalizes you twice: fees and credit damage. Set up autopay on whichever you choose. The missed payment guide covers the full recovery process.
Which BNPL Provider Should You Choose?
Choose Affirm for purchases over 00 that you want to pay off monthly. Choose Klarna for everyday shopping flexibility. Choose Afterpay for smaller fashion and retail purchases you can pay off in six weeks. There is no single best provider — the right choice matches your spending pattern.
Here is my recommendation by situation. Buying furniture, electronics, or travel? Affirm. Its longer payment terms and potential 0% APR offers make it the best fit for planned larger purchases. Shopping across many stores and want one tool that works everywhere? Klarna. Its browser extension and virtual card remove the merchant limitation entirely. Buying clothes, beauty, or lifestyle products from major retailers? Afterpay. Its pay-in-four simplicity and strong fashion merchant network were built for this.
One warning: do not use more than one BNPL provider simultaneously. Stacking obligations across Affirm, Klarna, and Afterpay creates overlapping payment schedules that are difficult to track, and no single app shows your total BNPL debt. Pick one, use autopay, and treat the payments like fixed bills. Check our research methodology for how we compare financial products across providers.
Sources
- Affirm — product terms, APR disclosure, and credit reporting policy (affirm.com)
- Klarna — payment options, fee schedule, and TransUnion reporting announcement (klarna.com)
- Afterpay — pay-in-four terms and late fee policy (afterpay.com)
- Experian — BNPL reporting integration details (experian.com)
- TransUnion — BNPL data inclusion announcement
- Equifax — Afterpay data sharing partnership
- Consumer Financial Protection Bureau — BNPL market report (consumerfinance.gov)