Chime has over 22 million account holders. SoFi Bank serves 8.6 million members. Varo Bank became the first consumer fintech to receive a national bank charter in 2020. Meanwhile, Bank of America, Chase, and Wells Fargo still hold roughly 33% of all US deposits, according to FDIC data. The divide is not neobank versus traditional anymore. It is which combination of accounts fits your actual banking habits. We verified every figure in this comparison through our published research methodology.
In this article
- What is a neobank exactly?
- How do fees compare between neobanks and traditional banks?
- Which offers better interest rates on savings?
- What can traditional banks do that neobanks cannot?
- Are neobanks safe for your primary checking account?
- What features should you compare before choosing?
- Frequently Asked Questions
What is a neobank exactly?
The distinction matters for deposit insurance. When Chime says your money is FDIC-insured, the insurance comes from Bancorp Bank or Stride Bank, Chime’s partner institutions. Your deposits are protected up to 50,000 per depositor per partner bank. The FDIC confirms this pass-through insurance arrangement on their deposit insurance page.
Traditional banks hold their own charter, accept deposits directly, and are examined by federal regulators. JPMorgan Chase, Bank of America, and Wells Fargo are all national banks supervised by the Office of the Comptroller of the Currency.
How do fees compare between neobanks and traditional banks?
| Fee type | Neobanks (typical) | Traditional banks (typical) |
|---|---|---|
| Monthly maintenance | -bash | .00-5.00 |
| Overdraft | -bash (SpotMe, buffer features) | 6.61 average (CFPB, 2024) |
| ATM (in-network) | -bash (55,000+ Allpoint ATMs) | -bash (own ATMs only) |
| ATM (out-of-network) | -bash-.50 | .50-.50 + owner fee |
| Minimum balance | -bash | 00-,500 to waive fees |
| Wire transfer (domestic) | -bash-5 | 5-5 |
| Paper statement | Not offered (digital only) | -bash-.00 |
The CFPB reports that Americans paid .7 billion in overdraft and NSF fees in 2023 alone. Neobanks have largely eliminated these charges. Chime’s SpotMe allows eligible members to overdraw up to 00 with no fee. SoFi covers overdrafts up to 0 automatically.
Which offers better interest rates on savings?
The math is straightforward. On a 0,000 balance, a 4.00% APY earns 00 per year. A 0.46% APY earns 6. That is 54 in lost earnings annually, compounding every year you delay switching. For a deeper breakdown of how these accounts work, read our guide on high yield savings accounts.
What can traditional banks do that neobanks cannot?
Cash deposits are the biggest gap. Most neobanks do not accept cash directly. Chime allows cash deposits at retail partners (Walgreens, CVS, 7-Eleven) through a service that charges .95 per transaction. That fee erases much of the savings advantage if you deposit cash frequently.
Lending is the second gap. SoFi offers personal loans and mortgages, but most neobanks do not underwrite mortgages, auto loans, or business lines of credit. If you want a relationship-based lending decision, a traditional bank or credit union is still the path.
Are neobanks safe for your primary checking account?
The Consumer Financial Protection Bureau has received complaints about account freezes at Chime and other neobanks. When a neobank’s fraud detection flags your account, resolving it requires phone or chat support, not a branch visit. This is a real downside for people who value face-to-face problem-solving.
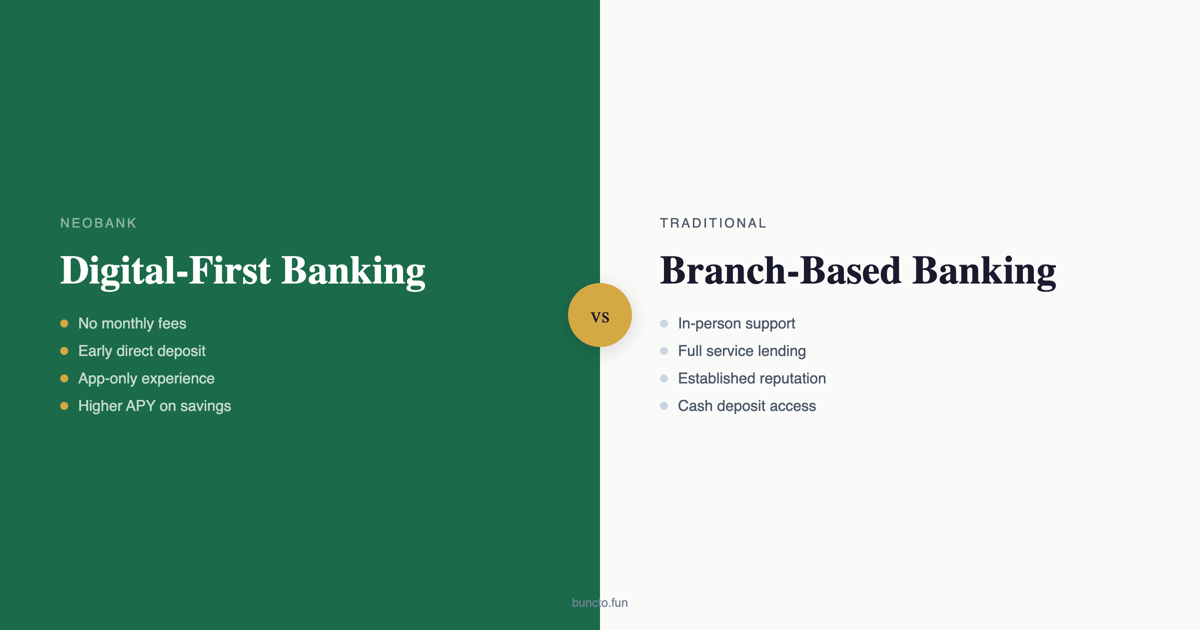
My honest take: for most Americans who are paid via direct deposit and rarely handle cash, a neobank is the better primary account. The fee savings, higher APY, and earlier direct deposit access outweigh the loss of branch services. But I would not recommend closing your traditional bank entirely until you have tested the neobank for 60 days. If you are considering the switch, here is how to do it without missing a paycheck.
What features should you compare before choosing?
| Feature | Chime | SoFi | Chase | Bank of America |
|---|---|---|---|---|
| Monthly fee | -bash | -bash | 2 (waivable) | .95 (waivable) |
| Savings APY | 2.00% | 4.00% | 0.01% | 0.04% |
| Early direct deposit | Up to 2 days | Up to 2 days | No | No |
| Overdraft buffer | SpotMe up to 00 | Up to 0 | 0 buffer zone | 5 buffer |
| ATM network | 60,000+ (Allpoint, Visa Plus) | 55,000+ (Allpoint) | 16,000 (own) | 16,000 (own) |
| Cash deposits | Retail (.95 fee) | No | Branch / ATM (free) | Branch / ATM (free) |
| Support | Chat, phone | Chat, phone, email | Branch, chat, phone | Branch, chat, phone |
Frequently Asked Questions
SoFi offers mortgages and home equity loans. Most other neobanks (Chime, Varo, Current) do not. For mortgage lending, traditional banks and credit unions still dominate. You can use a neobank for daily banking and a separate lender for your mortgage without any conflict.
If the neobank’s partner bank is FDIC-insured, your deposits are protected up to 50,000 regardless of what happens to the fintech company. If the neobank itself closes (like Simple did in 2021), your deposits transfer to the partner bank or are returned to you. The FDIC insurance covers the underlying bank, not the app layer.
Most neobanks do not use ChexSystems for account opening, which makes them accessible to people denied by traditional banks. Chime, Varo, and Current do not run ChexSystems checks. This is one of the strongest advantages for anyone with a negative banking history.
It is real, but the mechanism is simple. Employers send payroll files to the ACH network 1-2 days before the pay date. Traditional banks hold funds until the official date. Neobanks release the funds as soon as they receive the file. You get the same money, just sooner.
Sources
- FDIC, “National Rates and Rate Caps” — fdic.gov
- FDIC, “Deposit Insurance FAQs: Pass-through coverage” — fdic.gov
- CFPB, “Data Point: Overdraft/NSF Fee Reliance” — consumerfinance.gov
- Bankrate, “2024 Checking Account Survey” — bankrate.com
- Chime, “Fee Schedule” — chime.com
- SoFi, “Checking and Savings Account Details” — sofi.com