Quick answer: A credit report has four main sections: personal information, credit accounts (tradelines), inquiries, and public records. You can pull all three reports for free at AnnualCreditReport.com. Focus on account statuses, payment history, balances, and any negative marks. Errors on credit reports affect roughly one in five consumers, so checking yours at least once a year is not optional — it is basic financial hygiene.
Where Do You Get Your Credit Report for Free?
AnnualCreditReport.com is the only federally authorized source for free credit reports from all three bureaus — Equifax, Experian, and TransUnion. You can pull one report from each bureau per week at no cost. This is not a promotional offer. The Fair Credit Reporting Act mandates it.
Do not confuse your credit report with your credit score. The report is the raw data: every account, payment, inquiry, and public record associated with your identity. The score is a number calculated from that data. Free credit scores are available through most credit cards, neobanks, and apps like Credit Karma. The report itself comes from AnnualCreditReport.com.
Pull all three bureau reports at the same time for your first review. Creditors do not always report to all three bureaus, so your Experian report may show accounts that TransUnion does not, and vice versa. According to FICO.com, credit scores require at least one tradeline open for six months — if your report is empty, see our guide on building credit from scratch.
What Is in the Personal Information Section?
The personal information section lists your name, addresses, Social Security number (partially masked), date of birth, and employer. This section does not affect your credit score, but errors here can signal identity theft or file mixing.
Check for names you do not recognize, addresses you have never lived at, and employers you have never worked for. A misspelled name or old address is normal — bureaus accumulate historical data. But a completely unfamiliar name or address could mean someone else’s credit activity is merged with your file, which is called a “mixed file” and affects roughly 1 in 20 consumers.
If you find unfamiliar personal information, do not panic yet. Cross-check it against your other two bureau reports. If the same error appears on all three, it may indicate identity theft. If it appears on only one, it is more likely a data entry error by a creditor or the bureau itself.
How Do You Read the Accounts Section?
The accounts section — also called tradelines — is the most important part of your report. Each entry shows the creditor name, account type, credit limit or loan amount, current balance, payment history, and account status. This is where your score comes from.
| Field | What It Means | What to Check |
|---|---|---|
| Account type | Revolving (credit cards), installment (loans), or mortgage | Verify every account is yours |
| Account status | Open, closed, collection, charge-off | No account should say “collection” if you paid it |
| Credit limit / loan amount | Maximum credit or original loan balance | Should match your actual limit — errors affect utilization |
| Current balance | What you owe as of the last reporting date | Should be close to your actual balance |
| Payment history | Month-by-month record of on-time, late (30/60/90 day), or missed | Every late mark you do not recognize is worth disputing |
| Date opened | When the account started | Affects your average account age |
| Date of last activity | Last time the account was updated | Old dates on open accounts may mean the creditor stopped reporting |
Payment history drives 35% of your FICO score. A single “30 days late” notation can drop your score by 60 to 100 points depending on your overall profile. If you see a late mark you believe is wrong, dispute it with the bureau. You have the right to dispute any inaccurate information under the Fair Credit Reporting Act. Our research methodology covers how we verify credit-related claims.
What Are Hard and Soft Inquiries on Your Report?
Hard inquiries happen when you apply for credit and the lender checks your report. Soft inquiries happen when you check your own report, an employer screens you, or a lender pre-approves you. Only hard inquiries affect your score, and each one costs roughly 3 to 5 points.
Hard inquiries stay on your report for two years but only affect your score for about 12 months. Multiple inquiries for the same type of credit within a 14 to 45-day window — like shopping for a mortgage or auto loan — are usually grouped as a single inquiry by FICO’s scoring model. This is called rate shopping and does not penalize you for comparing offers.
Soft inquiries are invisible to your score. Checking your own report at AnnualCreditReport.com is always a soft inquiry. Credit monitoring apps like Credit Karma perform soft inquiries. Pre-approval offers from credit card companies are soft inquiries. You should see a complete list of both types in the inquiries section of your report.
What Are Public Records and Collections?
Public records on credit reports now include only bankruptcies. Tax liens and civil judgments were removed from credit reports in 2018. A Chapter 7 bankruptcy stays for 10 years. A Chapter 13 stays for 7 years. Collections are separate from public records and appear in the accounts section.
Collection accounts occur when an original creditor sells or assigns your unpaid debt to a collection agency. The collection appears as a new negative account on your report. Medical collections under $500 are excluded from credit reports under rules that took effect in recent years. Medical collections that were paid are also removed.
If you see a collection you do not recognize, request debt validation from the collection agency within 30 days of first contact. They are legally required to prove the debt is yours and the amount is accurate. If they cannot validate it, the collection must be removed from your report. For tips on managing your overall credit health, read our credit-building timeline.
What Does a Clean Credit Report Look Like?
A clean report shows all accounts as “open” or “closed” in good standing, zero late payments, no collections, no public records, and inquiries only from applications you recognize. The personal information section reflects your actual name and addresses.
Perfection is not the standard — most reports have minor quirks. An old closed account with a $0 balance is fine. A hard inquiry from a credit card application you remember is fine. What matters is the absence of negative marks: no late payments, no collections, no charge-offs, no bankruptcies.
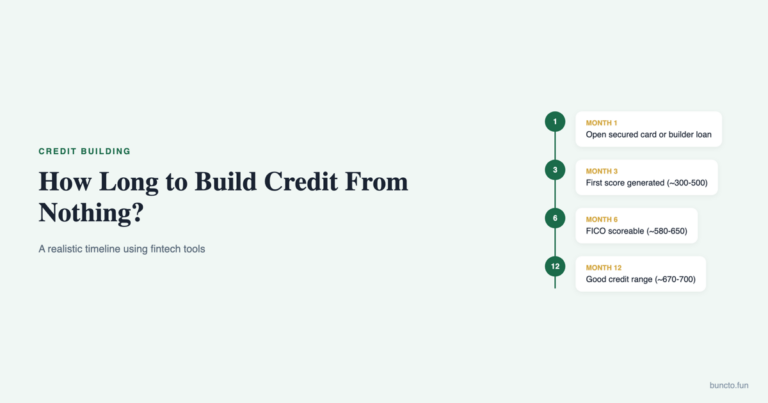
If your report is completely empty — no tradelines at all — you are “credit invisible.” FICO cannot generate a score without at least one tradeline open for six months. Start with a secured credit card or credit builder loan to create your first tradeline. Once reporting begins, check your report after six months to confirm the tradeline appears correctly.
Sources
- AnnualCreditReport.com — federally authorized free credit reports
- FICO — score factors and tradeline requirements
- Consumer Financial Protection Bureau — dispute rights and credit report accuracy
- Fair Credit Reporting Act — consumer rights regarding credit bureau data
- Experian, Equifax, TransUnion — bureau-specific report formats